

Trees rise from increasingly larger stacks of coins in an illustration of investment and economic growth.
We’ve developed a curious habit in America: We celebrate entrepreneurs who build businesses, create jobs and introduce products. But we’re often suspicious of the investors behind those achievements.
To many people, investors simply “make money from money.” Their income seems detached from real work, and their success often feels undeserved.
But what if our reaction to successful investors reveals as much about us as it does about them?
While working on a forthcoming article with economist Young Back Choi for the Journal of Markets & Morality, I found myself revisiting an old, uncomfortable idea: envy.
Most people use the words envy and jealousy interchangeably, but they’re not the same thing. Thomas Aquinas defined envy as sadness at another person’s good fortune. Jealousy, by contrast, arises when we fear losing something to which we have a rightful claim. A spouse may rightly feel jealous when a marriage is threatened by infidelity. With envy, your success doesn’t belong to me. I simply feel bad because something good happened to you.
That distinction matters because much of our uneasiness with investors looks less like jealousy and more like envy. Most critics are not claiming investors took something that rightfully belonged to them. Rather, they seem to be troubled that someone else became prosperous.
Consider an entrepreneur hoping to expand a business or launch a startup. Neither happens without capital. And capital exists only because someone chose not to spend money today and instead committed those resources to an uncertain future. Every investment begins with the same act: saving.
Investment is not as passive as critics may imagine. Investors delay consumption, bear risk and commit resources to uncertain projects. But because we see the rewards and not the sacrifices that precede them, investment income can seem mysterious or undeserved.
This misunderstanding has consequences. When people view economic life as a struggle over a fixed pie, another person’s gain naturally appears to be their loss. But Gordon Gekko, the fictional financier from the movie Wall Street, had it wrong. Wealth is not primarily transferred. It is created.

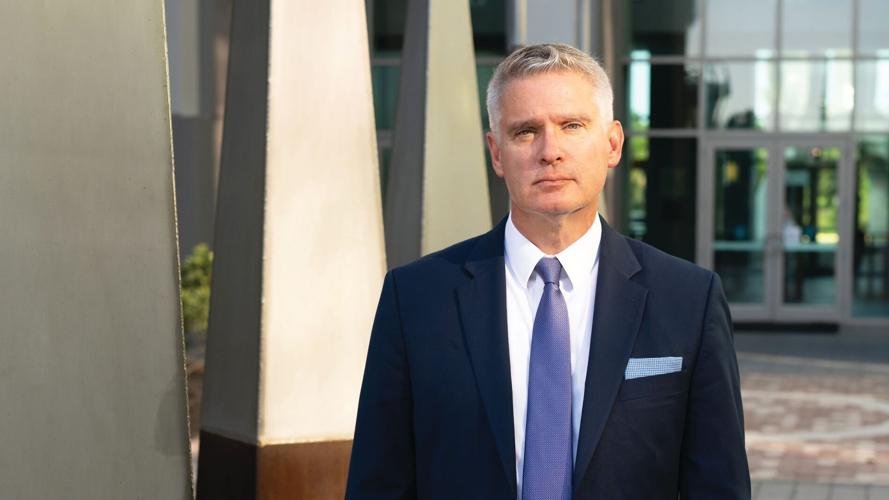
Victor V. Claar is an associate professor of economics in the Lutgert College of Business at Florida Gulf Coast University.
Before wealth can be redistributed, taxed, inherited, donated or spent, it must first be created. Entrepreneurs discern opportunities. Workers contribute their talents. Investors supply capital that transforms ideas into realities. New businesses, products and technologies improve our lives.
You can see the results throughout Southwest Florida: businesses, developments and opportunities that would not exist without entrepreneurs and investors taking risks.
The real miracle of a market economy is not that wealth changes hands. It is that new wealth is constantly being created in the first place.
Yet prosperity depends on more than individual effort; it depends on institutions. A healthy economy encourages entrepreneurs and investors to devote their creativity to serving customers and creating value. An unhealthy economy encourages them to devote that same creativity to navigating bureaucracy, seeking political favors or influencing regulatory decisions.
Such “gaming the system” squanders human potential. Every hour spent pursuing a regulatory advantage is an hour not spent creating value. Every dollar devoted to political influence is a dollar not invested in productive enterprise. Society prospers when talented people focus on creating value rather than redistributing it.
Of course, not every fortune is earned honestly. Cronyism and political favoritism deserve scrutiny. But it is a mistake to assume wealth itself is evidence of wrongdoing. Dishonest wealth does not erase the value created by honest saving, investment and entrepreneurship.
Aquinas understood something that remains relevant centuries later: Envy directs our attention away from improving our own condition and toward resenting someone else’s success.
The next time we encounter a successful investor, perhaps we should ask different questions. What risks did they bear? What opportunities did they recognize? What value did they help create? And which public policies encourage — or impede — those activities?
If we care about prosperity, our focus should be less on resenting success and more on understanding how wealth is created — and on fostering institutions that encourage innovation, investment and human flourishing.
Victor V. Claar is an associate professor of economics in the Lutgert College of Business at Florida Gulf Coast University and an affiliate scholar of the Acton Institute.
(0) comments
Welcome to the discussion.
Log In
Keep it Clean. Please avoid obscene, vulgar, lewd, racist or sexually-oriented language.
PLEASE TURN OFF YOUR CAPS LOCK.
Don't Threaten. Threats of harming another person will not be tolerated.
Be Truthful. Don't knowingly lie about anyone or anything.
Be Nice. No racism, sexism or any sort of -ism that is degrading to another person.
Be Proactive. Use the 'Report' link on each comment to let us know of abusive posts.
Share with Us. We'd love to hear eyewitness accounts, the history behind an article.